Business insurance
Business Property & Auto Insurance
Protect what keeps your business moving.
Your workspace, equipment, and vehicles all play a part in your business. We help you consider them together, with coverage shaped around how you work.
Schedule a CallA complimentary 30-minute conversation.
The basics
How do property and auto coverage work together?
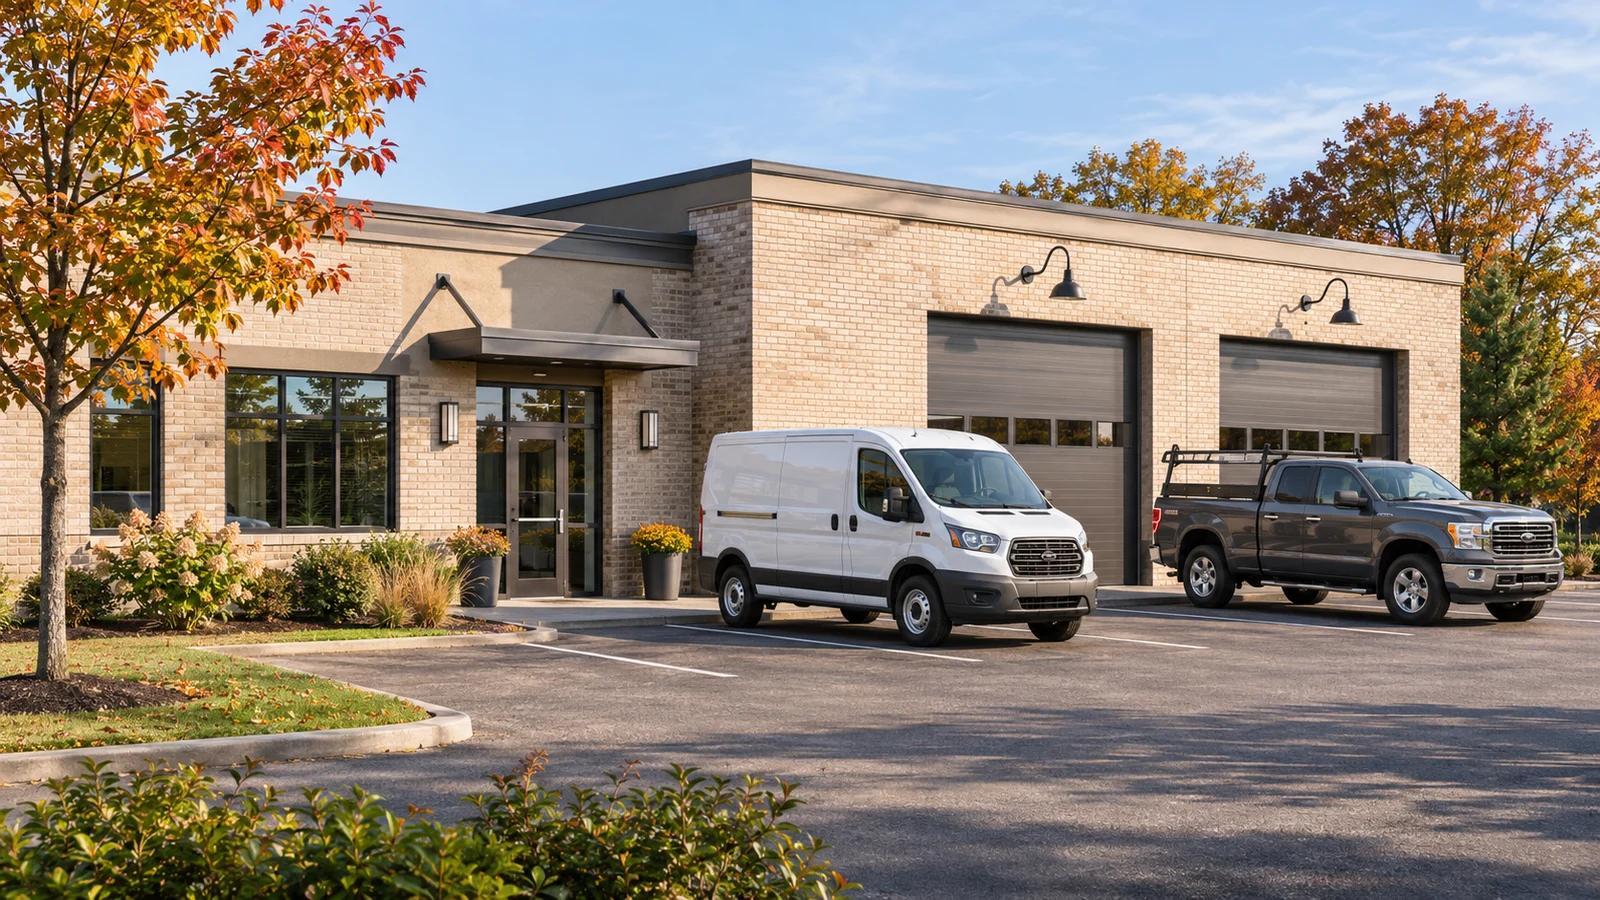
Commercial property insurance helps protect covered buildings and business belongings. Commercial auto insurance addresses covered vehicle-related liability and, when selected, damage to insured vehicles. They serve different purposes, but reviewing them together helps connect the details of your business.
Buildings and belongings
Consider the space you own, equipment, furniture, and inventory. If you lease, your contents and improvements may still need coverage separate from the landlord’s policy.
Business income
Business income and extra expense coverage can help after covered damage interrupts operations. Covered causes, waiting periods, limits, and the restoration period affect what is payable.
Business vehicles
Review liability for accidents involving covered vehicles, plus collision and comprehensive options for damage to those vehicles. Drivers, ownership, and actual use all matter.
Rented and personal vehicles
Hired and non-owned auto liability can address certain exposures when your business rents vehicles or employees use personal cars for work. Physical damage requires separate consideration.
Coverage should keep pace with your business.
Your space is changing.
A new location, lease, or renovation is a good reason to revisit property values and responsibilities.
Your work is on the move.
Deliveries, service calls, and tools traveling between jobs deserve a closer look at vehicle and equipment coverage.
Your operation is growing.
New vehicles, drivers, equipment, or inventory can change the protection your business needs.
Start with the right questions.
What would it take to repair or replace your property?
Discuss current values, replacement cost versus depreciated value, and any insurance-to-value requirements. Include leased equipment, improvements, and seasonal inventory changes.
Where does your equipment go?
Property kept at a fixed location and tools carried to job sites may need different coverage. Tell us about equipment in transit, stored in vehicles, or used away from your premises.
Who drives, and how are the vehicles used?
Bring the full picture: owned and leased vehicles, rentals, employee errands, deliveries, and any personal use. Coverage should reflect the business entity and actual driving activities.
How would an interruption affect your cash flow?
Review ongoing expenses, likely recovery time, and ways to continue operating. Your accounting information can help inform the discussion of business income limits.
One business. A connected conversation.
Thoughtful protection starts with understanding how the pieces fit together.
Start with your business.
Tell us how you work, what has changed, and what you want your coverage to accomplish.
Connect the details.
We review relevant policies together, compare options, and explain the differences that matter to you.
Keep the conversation going.
As your business changes, we help you revisit your coverage and consider the next steps.
Already work with Monocacy’s accounting or wealth team? With your permission, we can bring relevant purchases, location changes, and business plans into the insurance conversation. You are also welcome to work with us for insurance alone.
Common questions.
Can I rely on my personal auto policy?
Some personal policies allow limited business use; others exclude particular activities or vehicles. Explain how the vehicle is used and titled before relying on personal coverage. Your business may need commercial auto or hired and non-owned auto liability.
Does my landlord’s insurance protect my business belongings?
Do not assume it does. Your lease and policies determine who insures the building, improvements, and contents. Review your own equipment, inventory, and responsibilities separately.
Are tools stolen from a vehicle covered by auto insurance?
An auto policy does not automatically insure the tools or inventory inside a vehicle. Review mobile equipment or inland marine options and any theft conditions for property carried between locations.
Does business income insurance cover every closure?
No. Coverage typically requires a qualifying covered loss and is subject to the policy’s conditions. A slowdown in sales or an excluded event is not automatically covered.
What about claims above my auto liability limit?
Commercial umbrella coverage may provide another layer above an eligible underlying auto liability policy. The policies must work together, and exclusions still apply. Explore commercial umbrella insurance.
Further reading: Maryland Insurance Administration business owner’s guide (PDF).
Let’s look at the whole operation.
Talk with us about your property, vehicles, and plans. We’ll help you connect the details and compare your options.
Complimentary · 30 minutes